

RedotPay: Crypto Card & Pay
Red Dot Technology Limited
- 4.3
- 1.27K Reviews
- 5.00M
- Downloads
- Free
- Price
Screenshots
RedotPay: Crypto Card & Pay Pros and Cons
Pros
- Supports crypto-funded payments with a virtual card option.
- Useful for spending digital assets at merchants accepting Visa cards.
- Offers in-app card and transaction management tools.
- May provide convenient access to multiple supported cryptocurrencies.
- Can simplify crypto payments without manually converting assets first.
Cons
- Availability and features may vary depending on your country.
- Fees and exchange rates can reduce the value of smaller transactions.
- Identity verification is required before using key services.
- Crypto prices can change quickly, affecting your available spending value.
- Customer support response times may vary during account or payment issues.
 Analysis by All-app
I approached RedotPay as a finance app for people who want to use cryptocurrency in more ordinary spending situations, rather than leaving digital assets inside an exchange or wallet. Its central idea is straightforward: keep crypto in a secure wallet, then use the app to manage spending, swapping, and sending from one place. In practice, that makes it more interesting than a basic price-tracking app, but also more demanding than a normal banking app because the value of crypto can change and every transaction deserves attention.
The app is developed by Red Dot Technology Limited and is available free of charge. That matters when judging its value: there is no purchase price to weigh against the features at the point of installation. The free entry makes it easy to explore, although “free” does not automatically mean that every possible transaction, conversion, or card-related action will have no cost. I would treat the download as free access to the service, not as a promise that crypto activity itself is costless.
RedotPay has built a sizeable audience, with more than five million installs and an average score of 4.3 from roughly seventy-two thousand ratings. Those figures suggest that the app has reached well beyond a small group of crypto enthusiasts. The age classification is Everyone, and the app runs on Android seven or later, so the technical entry barrier is relatively low for compatible Android phones. Its current version is 3.13.1, which is useful context for anyone comparing an older review with the experience offered today.
How RedotPay fits into everyday crypto spending
I find RedotPay most useful when I treat it as a way to connect a crypto balance to a specific spending or transfer task, rather than as a replacement for my everyday bank account. That distinction helps me decide what belongs in the app and what should stay elsewhere. From there, the key question is whether its current, payment-oriented approach suits the way I already handle crypto.
A wallet, payment tool, and transfer hub in one place
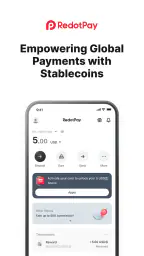
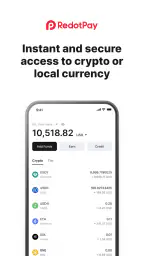
What I like about the concept is that it connects several actions that are often split between different services. A conventional crypto exchange may be good for buying or swapping assets, while a separate wallet may handle storage and another payment product may be needed for spending. RedotPay aims to bring those jobs closer together. I can think about the balance I hold, the assets I may want to exchange, and the money I want to send without constantly moving between unrelated apps.
That convenience is most useful when the user already has a clear reason to hold crypto. For example, someone who receives digital assets, keeps part of them for later, and occasionally wants to spend them internationally may prefer a single interface. The app’s positioning around spending crypto like cash gives it a practical angle: it is not only about watching market movements, but about making a balance useful in daily life.
Still, I would not confuse a unified interface with a simplified financial decision. The app can put wallet, swap, send, and payment-related tasks near each other, but the user still needs to understand which asset is being used, what amount is being moved, and whether the recipient or merchant experience matches the intended payment method. RedotPay reduces app switching; it does not remove the need for careful checking.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
A realistic travel scenario
Imagine I am travelling and want to keep some spending money in crypto rather than relying entirely on a traditional bank card. Before leaving, I could use the wallet side of the app to review what I hold and decide which balance is appropriate for spending. During the trip, I might use the payment function for an everyday purchase, send funds to another person in my group, or swap one asset when the original balance is inconvenient for the situation.
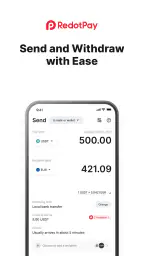
The advantage is organizational. I do not need to remember which service contains the funds and which one handles the transfer. If a friend needs reimbursement, a send function in the same environment may be quicker than converting everything back to ordinary money first. If I am paying attention to exchange rates, I can also make a deliberate choice about whether to swap before spending or leave the balance as it is.
The trade-off is that a trip is exactly when mistakes are expensive and stressful. A traditional bank card usually presents a familiar amount in a familiar currency. A crypto payment requires more awareness of the asset, conversion, and timing. I would use RedotPay for this scenario only after testing a small transaction at home and learning the app’s confirmation flow. I would not make it my sole source of travel funds.
What the free price means in practice
The app can be installed without paying for access, which gives it a clear advantage over a finance product that requires a subscription before the user can decide whether it fits. I can explore the layout, understand the wallet workflow, and see whether the combination of sending, swapping, and spending suits my habits without committing money to the download itself.
That free access is valuable for two different audiences. A newcomer can learn whether managing crypto in a payment-oriented app feels comfortable. An experienced user can compare the workflow with an existing exchange or wallet before deciding whether to add another service. In both cases, the sensible approach is to begin with a limited balance and inspect each transaction screen rather than assuming that the absence of an app charge makes every action equally economical.
I also think the free model changes how I judge the app. I am not asking whether it replaces every financial service for one fixed price. I am asking whether its convenience is worth adding another crypto account to my routine. If I already have a reliable exchange, a self-custody wallet, and a card that works well abroad, RedotPay must save enough time or provide enough flexibility to justify that extra layer.
The strongest value is workflow, not speculation
The most useful feature set is the way the app links holding and using crypto. Many people can already find a chart, buy an asset, or send a token somewhere. The more meaningful question is what happens after that. RedotPay is aimed at the point where a crypto balance becomes part of a payment routine, and that makes it more practical than tools designed mainly for trading screens.
One non-obvious benefit is the ability to separate the decision to hold crypto from the decision to spend it. I can keep a balance in the wallet, then decide later whether to send, swap, or use it for a purchase. That separation encourages a more deliberate habit than immediately converting every incoming asset. It also makes the app useful for someone who wants occasional access to crypto spending without turning every transaction into an active trading session.
Another useful workflow is planning a transfer before a busy moment. If I know I will need to reimburse someone, I can check the asset and amount in advance instead of opening the app while standing at a checkout or waiting for a payment to go through. This sounds minor, but it reduces the chance of selecting the wrong balance or rushing through a confirmation. The app’s value is often found in this preparation rather than in any single button.
A third insight is that a spending-focused crypto app should be judged by how clearly it helps users distinguish “available to spend” from “held for later.” Even when the interface is clean, I would keep my own simple rule: maintain a small spending balance and avoid treating the entire wallet as a daily budget. That habit limits the damage from an impulsive payment and makes market movement less disruptive to ordinary expenses.
Where it differs from ordinary banking apps
Compared with a standard banking app, RedotPay offers more direct access to crypto operations. A bank app normally starts with familiar currency balances, predictable payment records, and established transfer habits. RedotPay is more flexible for digital assets, but that flexibility comes with additional choices and risks. The user may need to think about the asset being used, the conversion path, and whether the transaction is appropriate for the intended recipient.
Compared with a typical crypto exchange, its appeal is the payment orientation. Exchanges tend to make buying and selling the central activity, while RedotPay puts more emphasis on using and moving a crypto balance. That can be a better fit for someone who wants practical access rather than a screen full of trading tools. On the other hand, a dedicated exchange may be preferable for users whose main goal is advanced market analysis or frequent trading.
Compared with a self-custody wallet, the important distinction is convenience versus personal control. RedotPay is designed to make spending and transfers approachable inside a managed app experience. A self-custody wallet may be the better choice for someone who wants direct responsibility for keys and prefers to manage every security detail independently. I would not choose RedotPay solely because it looks simpler if my primary requirement is maximum control over custody.
Security habits matter more than the download price
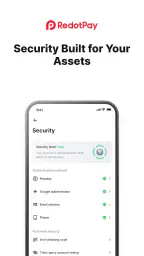
The app presents itself as a secure wallet, but I would still treat security as a personal process rather than a label. I would install it only on a phone I keep updated, use a strong device lock, avoid discussing recovery or access details with anyone, and review every recipient before confirming a send. These habits are especially important because a payment-oriented wallet may be opened in public, while travelling, or during a rushed purchase.
I would also avoid keeping all of my crypto in one place simply because the app combines several functions. Convenience can encourage concentration. A smaller operational balance is easier to monitor and better suited to everyday spending, while long-term holdings may deserve a separate strategy. This is not a criticism unique to RedotPay; it is a practical boundary I would apply to any wallet that makes spending easy.
Before relying on the app abroad, I would test the complete journey: adding or receiving funds, checking a balance, initiating a small send, and understanding the confirmation screen. I would also keep a backup payment method. If a phone is lost, a connection fails, or a payment is declined, the problem is not solved by the fact that the wallet contains money. A payment app should be part of a travel plan, not the entire plan.
Friction points I would take seriously
The first limitation is the complexity inherited from crypto itself. A newcomer may see wallet, swap, send, and payment functions as simple variations of the same task, but they are not interchangeable. Sending the wrong asset or using the wrong destination can create a serious problem. RedotPay may make the interface more accessible, yet the user still needs basic crypto literacy before moving meaningful amounts.
The second limitation is value uncertainty. The app is free to download, but crypto prices can move independently of the user’s daily budget. A balance that feels adequate one day may buy less later. That makes RedotPay a poor substitute for a conventional account used for rent, groceries, or emergency savings. I would use it for planned discretionary spending, not for money whose stability matters more than flexibility.
The third limitation is that one convenient app can blur separate financial roles. A wallet is not automatically a bank account, a swap tool is not automatically the cheapest conversion route, and a payment card or payment function is not automatically accepted everywhere a traditional card is accepted. I would read each screen carefully and avoid assuming that “worldwide” means universal acceptance in every merchant, country, or situation.
There is also a learning curve for people who have never managed crypto. The age rating of Everyone describes the app’s content classification, not the financial complexity of the decisions inside it. An adult beginner may need time to understand balances, transfers, and swaps, while a younger user should have appropriate guidance before handling real funds. I would not hand the app to a first-time user with a large balance and expect the interface alone to teach sound financial judgment.
Who is likely to get the most value?
I see the strongest fit for an existing crypto user who wants a practical spending layer. If I already understand basic wallet transfers and want to send or use assets without moving through several services, RedotPay’s free access makes it worth testing. It may also suit frequent travellers, remote workers, or people who regularly exchange digital assets with others and value having wallet and payment-related actions together.
The app can also help someone who wants to experiment cautiously. Because there is no charge to install it, I can compare its workflow with my current setup using a small amount. The right test is not whether the screen looks modern; it is whether I can complete a normal task without confusion. Can I identify the balance I intend to use? Can I review the recipient? Can I understand what I am confirming? Those answers tell me more than the download page.
I would be more hesitant to recommend it to someone who wants a simple everyday bank replacement. If the priority is stable currency, predictable budgeting, familiar customer support, and minimal exposure to market movement, a traditional banking app is a better starting point. Likewise, an active trader may prefer a specialized exchange, and a security-focused long-term holder may prefer a self-custody arrangement.
It is also not the right choice for someone unwilling to maintain basic security discipline. A finance app can make transactions convenient, but convenience increases the need to pause before confirming. If I know I tend to rush payments, reuse weak passwords, or store sensitive details carelessly, I would solve those habits first rather than relying on the app to protect me from every mistake.
My practical way of trying it
I would begin by installing the free app on a compatible Android device and spending time in the interface before transferring a meaningful balance. I would identify where the wallet balance appears, how a swap is initiated, how a send is reviewed, and where payment activity can be checked. I would then perform the smallest sensible test, keeping notes about the asset, destination, and purpose so that the result is easy to evaluate.
After that, I would create a personal spending rule. For example, I might use only a limited amount for travel or small purchases and keep long-term holdings elsewhere. I would review the balance before each larger payment, avoid making decisions based solely on a short-term price move, and keep an alternative payment method available. This approach lets me test the app’s convenience without turning an experiment into a financial dependency.
I would also compare the complete cost of a real task with my usual alternative. The app itself is free, but the relevant comparison is the amount that leaves my wallet, the amount the recipient receives, and the effort required to complete the transaction. If a regular bank card is simpler for a particular purchase, I would use the bank card. If RedotPay makes a crypto transfer or cross-border spending workflow more convenient for my specific situation, then its value comes from that convenience rather than from the absence of an installation fee.
My verdict on value
RedotPay is worth trying when the goal is to make crypto more usable in everyday payment and transfer situations. Its free entry, broad audience, and combination of wallet, swap, send, and spending functions give it a clear practical identity. I especially like it for users who already hold crypto and want a more direct route from holding an asset to using it.
My recommendation is conditional rather than universal. I would choose it as a supplementary finance tool, start with a modest balance, and keep a conventional payment option nearby. I would not use it as my only account, my emergency fund, or my automatic replacement for a bank app. The app can simplify the workflow around crypto, but it cannot make crypto behave like stable cash or remove the responsibility of checking every transaction.
In the end, the free price makes the decision easy to test, not automatically easy to justify long term. If RedotPay saves me from switching between several crypto services and its payment workflow matches the way I actually spend, it delivers useful value without an upfront purchase. If I mainly want stable budgeting, advanced trading, or maximum custody control, another type of financial app will serve me better. For the right user, it is a practical bridge between a crypto wallet and real-world spending; for everyone else, it may simply add complexity to a system that already works.
Frequently Asked Questions
What is RedotPay: Crypto Card & Pay, and how does it work?
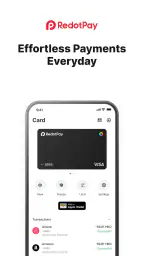
RedotPay is a digital payment app designed to let users spend supported cryptocurrencies through a virtual or physical crypto card, depending on availability in their region. After creating an account and completing any required identity verification, users can manage funds in the app, request a card, and use it for eligible online or in-store purchases. The exact conversion process, supported assets, and card features may vary by country.
Which cryptocurrencies and payment methods does RedotPay support?
RedotPay supports selected digital assets and payment options, but the available list can change over time and may differ between countries. Before transferring funds, check the in-app wallet and deposit screens carefully to confirm the supported cryptocurrency, blockchain network, and minimum amounts. Sending an unsupported asset or using the wrong network can result in delayed recovery or permanent loss, so users should verify all transaction details before confirming.
Are there fees for using RedotPay or its crypto card?
RedotPay may charge fees for services such as card issuance, delivery, top-ups, cryptocurrency conversion, withdrawals, transfers, or foreign-currency transactions. Some merchants or ATM operators may also apply their own charges. Because fees and limits can change, the most reliable information is shown inside the app before completing an operation. Users should review the final confirmation screen and the current fee schedule rather than assuming every payment is free.
Is RedotPay safe to use, and what verification is required?
RedotPay uses account-security measures such as login protection, transaction controls, and identity verification requirements, but no financial application is completely risk-free. Depending on the user’s country and account activity, RedotPay may request personal documents for Know Your Customer checks. It is important to enable available security features, use a unique password, avoid sharing verification codes, and contact official support only through the channels provided in the application.
Can I use the RedotPay card everywhere, and what happens if a payment is declined?
The RedotPay card can generally be used wherever the relevant card network and merchant category are supported, but acceptance is not guaranteed. Certain countries, merchants, subscription services, offline terminals, ATMs, or restricted industries may be unavailable. A payment can also fail because of insufficient balance, verification issues, spending limits, network problems, or merchant restrictions. If a transaction is declined, check the app notification, available balance, card status, and regional limitations before trying again.


